Most business owners don't think about their financial reports until someone asks for them. A bank wants three years of statements. An investor wants to see last quarter's cash position. Suddenly you're digging through folders, and the numbers you thought were fine turn out not to add up.
Financial report preparation works best as a habit, not a scramble. Here's how to do it properly, whether you're after a loan, an investor, or just a clearer view of your own business.
What financial report preparation actually involves
It means gathering your financial data, checking it, organizing it, and presenting it so someone else can follow it. That "someone else" matters. A report only you can read isn't doing its job.
You'll usually work with three business financial reports:
- Income statement: revenue, expenses, and the profit or loss left over for a set period.
- Balance sheet: what the business owns and owes on a specific date.
- Cash flow statement: where cash came in and where it went.
These three need supporting records behind them, such as invoices, bank statements, and payroll files. They also need a short explanation when something looks odd. A sudden drop in cash with no comment attached tends to make readers nervous.
What lenders and investors are really looking for
A banker reading your loan application is asking one thing: will this business pay me back? Everything else follows from that. They look at income stability, existing debt, and whether your cash can cover the new repayments.
Investors care about repayment less and growth more. They want to see how you make money, how margins are moving, and what their funds would actually do.
Neither expects perfection. I've seen decent businesses turned down because their reports had conflicting totals and nobody could explain why. The numbers weren't bad, but the paperwork made people doubt them. Reports that are complete, consistent, and traceable to real records go a long way.
Step 1: Get your records in order
Start by collecting everything for the period you're reporting on: bank statements, sales invoices, supplier bills, payroll, loan statements, tax documents, receipts, and a list of major equipment. Focus on having clean business records.
Accounting software helps, but don't trust it blindly. It only knows what someone typed in. A missing customer payment, an invoice entered twice, or a fuel receipt filed under office supplies can all quietly skew your results.
Watch the cut-off dates too. If you're reporting on the quarter ending September 30, the report should include expenses that belong to that quarter even if you haven't paid them yet.
If your receipts live in a shoebox or a messy inbox, fix that first. Doing a little each week beats a frantic weekend before a deadline.
Step 2: Reconcile your accounts
Account reconciliation is the dull step that saves you the most trouble. You compare your books against outside records, mainly bank statements, and make sure the two agree.
Say your books show $25,000 in the bank and the statement says $23,800. That $1,200 gap has an explanation. Maybe a check hasn't cleared. Maybe a bank fee never got recorded. Maybe someone keyed a payment wrong. Until you find it, you can't trust any report built on top of that balance.
Bank accounts are just the start. Credit cards, loans, customer balances, and supplier balances all deserve the same treatment. A polished report built on unreconciled numbers is just a nice-looking mistake.
It also pays off when someone asks questions. If a lender points at a figure and asks where it came from, you want to answer in seconds.
Step 3: Build the three statements
Financial statement preparation is fairly quick when you have clean reconciled records.
Do the income statement first, then the balance sheet. The cash flow statement comes last, and don't treat it as an afterthought. Profit and cash are not the same, and plenty of owners learn that the hard way. You can show a healthy profit and still be unable to make payroll because customers are paying late. Or you can take out a loan, watch your bank balance jump, and be no better off.
Read the three statements side by side. When they tell the same story, you're probably in good shape. When they don't, something needs another look.
If the report is going outside your business, check whether the recipient wants a specific accounting framework, format, or level of review. Some lenders require reviewed or audited statements, and it's better to know that up front.
Step 4: Make the report lender-ready
A lender-ready financial statement saves the reader from doing detective work. Give them what they asked for, in the order they'd expect it.
Beyond the core statements, lenders often want a debt schedule, an accounts receivable aging report, payables details, recent bank statements, and business tax returns. If you're asking for money to expand or buy equipment, they may also want projections.
Keep projections grounded. If you're forecasting 30% sales growth, say why. Signed contracts, a second location, or new capacity are real reasons. "We feel optimistic" is not.
Be upfront about your existing debt, too. Lenders don't only care what you earn. They care how much of it is already spoken for.
Requirements differ between lenders, loan types, and countries. Ask for their document checklist before you start, not after you've submitted.
Step 5: Make it investor-ready
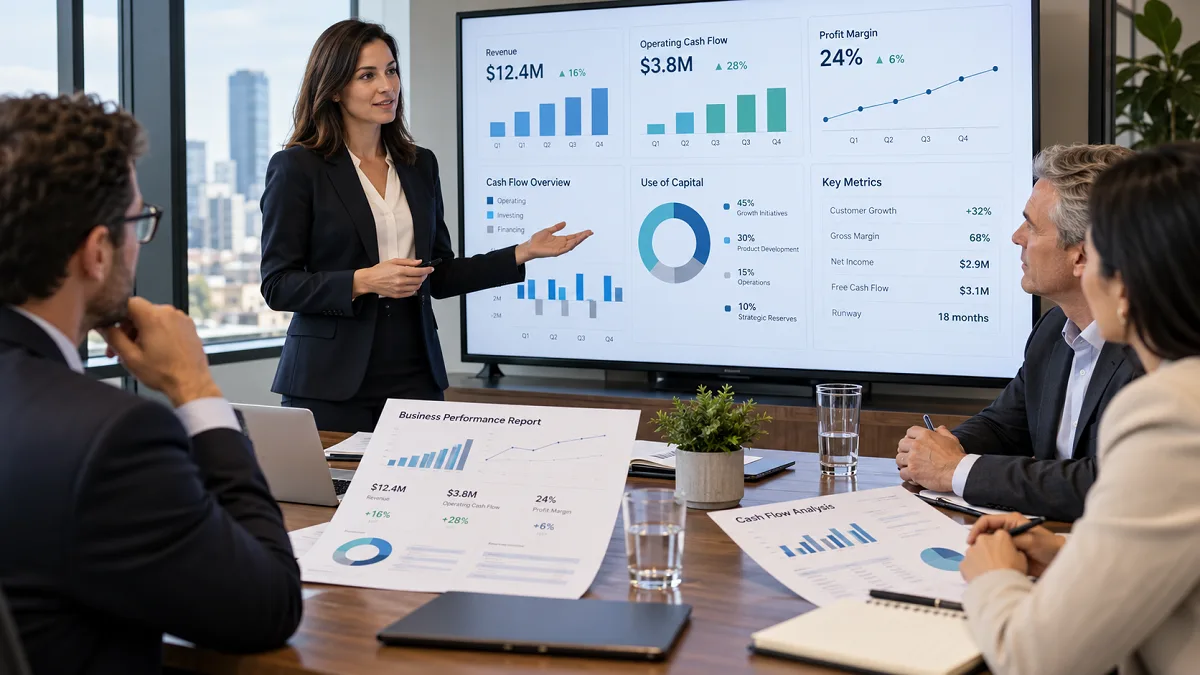
Investors read the past to judge the future. Investor-ready financial reports would need to show your revenue trend, your largest costs, your margins, and your cash flow. If you've grown steadily for three years, make that obvious. If profit dipped, say so, say why, and say what you changed.
Add a forecast covering revenue, costs, and cash needs, with the assumptions written down. Then explain what you'll do with the money: hiring, product development, equipment, a new market.
Keep the design simple. A couple of clear charts can help. Twenty crammed pages won't.
Step 6: Explain what the numbers mean
Totals alone don't tell a story. Say revenue rose 15% but profit barely moved. That could look like good news until you notice supplier prices went up, payroll grew, and marketing spend jumped. A two-sentence note clears that up.
Do the same for cash. If it dropped sharply, tell the reader why. Seasonal slowdown? A big equipment purchase? A few large customers paying late?
Comparisons help a lot. Put this month next to last month, this quarter next to the same quarter last year, and actual results next to budget. Patterns show up that way which you'd otherwise miss.
And skip the jargon where plain words work. Nobody has ever been impressed by a report they couldn't understand.
Step 7: Check everything before you send it
Do a proper final review. Confirm the balance sheet actually balances, the cash flow ties back to your records, the dates are consistent, and every requested document is attached. Look into any accounting reconciliation differences that are still unexplained.
Then check the small stuff: company name, dates, currency symbols, headings. Typos in business financial reports suggest carelessness, and that's an unhelpful impression to give someone deciding whether to trust you with money.
For a major loan or funding round, pay a financial reporting services company to review it. A fresh pair of eyes will catch things you've stopped seeing. Keep your supporting documents organized so you can trace any figure back to its source, and share the report securely with only the people who need it.
Where financial reporting services fit in
If you're already juggling sales, staff, and day-to-day problems, producing clean reports on a regular schedule is hard. That's why many small businesses bring in outside help.
Depending on the provider, financial reporting services can cover bookkeeping reviews, reconciliation, statement preparation, cash flow reports, management reporting, and help assembling lender or investor packages. The real value is consistency. Your records stay current, so you aren't starting from zero every time funding comes up.
When you compare providers, ask about their experience with businesses like yours, how they review their own work, which software they use, and what costs extra. Get that in writing.
Remember, outsourcing the work doesn't outsource the responsibility. It's still your business and your signature, so read what they give you.
Mistakes that weaken a good report
Inaccurate financial reporting can be bad for your reputation.
- Mixing personal and business spending. It muddies your real performance. Keep the two separate.
- Skipping reconciliation. Unchecked balances lead to wrong statements and awkward questions.
- Inflating forecasts. Optimism with no evidence behind it costs you credibility fast.
- Leaving out debts. A missing liability makes your position look better than it is, and lenders usually find it anyway.
- Waiting until you need funding. Rushed reports have gaps and errors.
- Over-complicating things. Too much detail with no explanation hides what readers actually need.
Accounting Report Preparation With AccountiPro
Financial reporting is more than an admin chore. Done well, it shows you where your business stands, helps you plan, and tells lenders and investors you take the money side seriously.
Sometimes, it may feel stressful or feel like a burden too. Working with a financial reporting service like AccountiPro, investors and lenders both can feel more confident about your numbers.
We keep your records current, clean and accurate. With AccountiPro, you no longer need to stress about deadlines, or preparing investor-ready financial reports. Contact us today for more information on how we can support your business in reaching its long-term goals.